What to know
- Marqeta announced the Coinbase collaboration on 16 October 2026 for enterprise card offerings.
- The issuer release assigns custody and fiat conversion to Coinbase alongside Base settlement infrastructure.
- Availability, customer charges and exception handling need programme-specific evidence rather than assumptions.
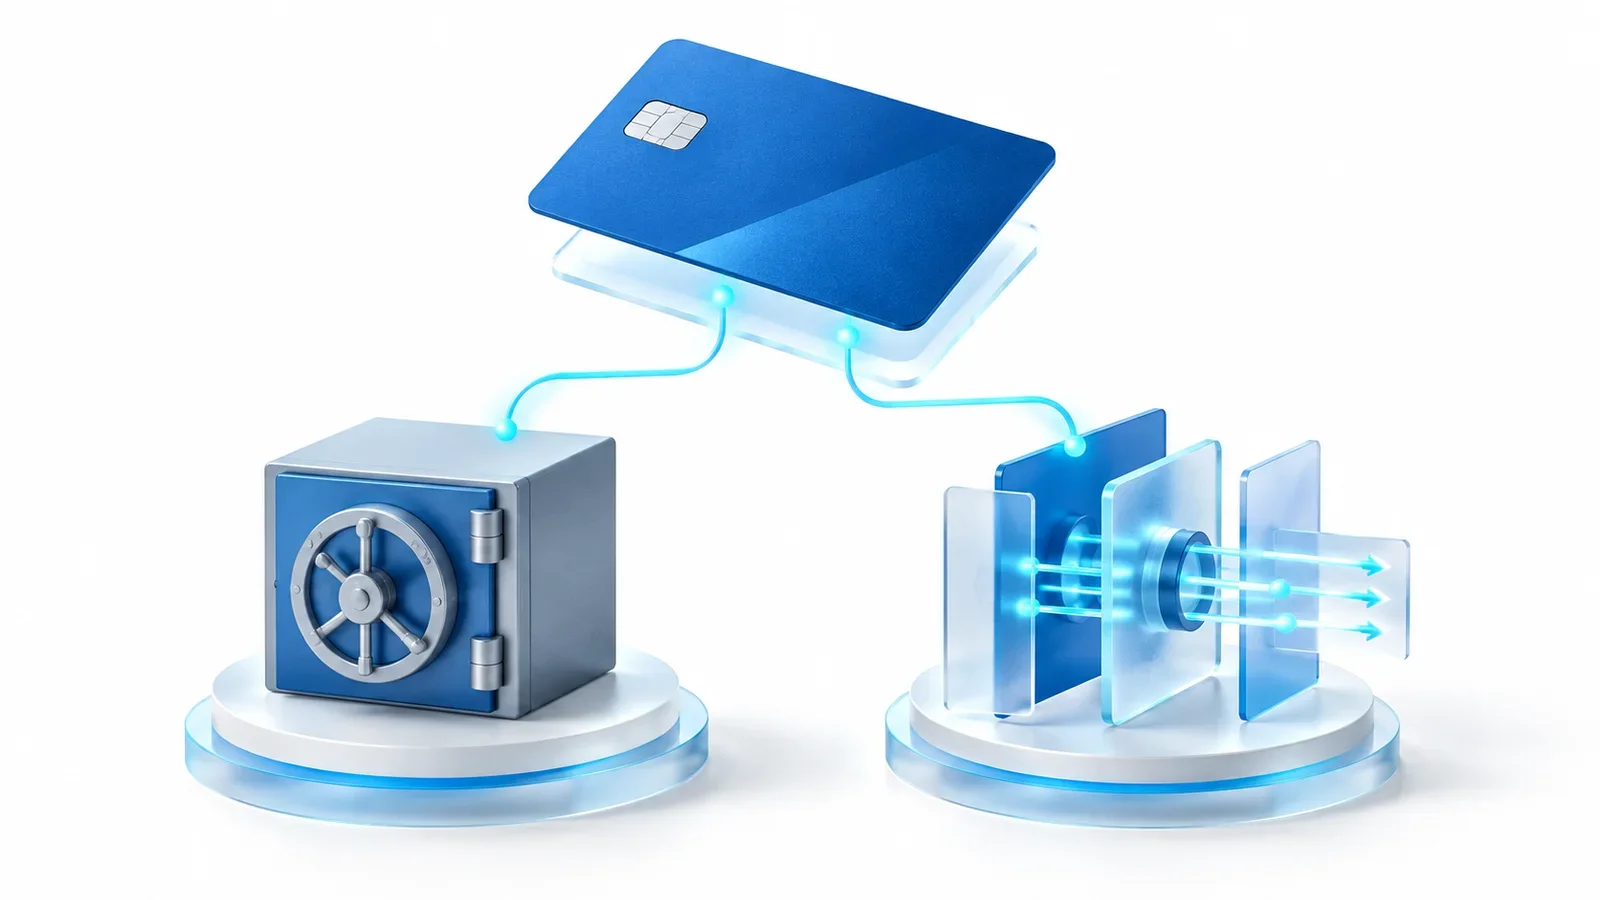
Who controls the money between a stablecoin balance and an ordinary card purchase? That is the useful question behind Marqeta’s 16 October 2026 collaboration announcement with Coinbase. Marqeta says the arrangement will let its business customers offer cards funded from stablecoin holdings, with Coinbase supplying custody, conversion into fiat money and settlement infrastructure on Base.
The announcement describes an expansion of infrastructure for enterprise customers. It should not be read as confirmation that a particular consumer can apply for a particular card today. Nor does it establish that a shop accepting one of these cards would itself receive stablecoins. The release’s stated conversion role is central to understanding the proposal.
Separate the balance from the purchase
A business evaluating this design should request a transaction map rather than rely on the phrase stablecoin-backed card. That map should identify where the customer’s balance sits, which party can move it, when conversion is triggered and what happens if a purchase is authorized but later reversed. These are evaluation questions, not additional features confirmed by the announcement.
One useful exercise is to trace a hypothetical purchase through authorization, conversion, completion and refund. At each transition, record the responsible provider, the denomination of the customer’s claim and the evidence retained for reconciliation. A successful checkout alone cannot answer whether the balance history and the merchant transaction can be reconciled after an exception.
Ask for an exception path before a rollout plan
The same review should examine insufficient balances, unavailable conversion and disagreements between a card transaction record and a wallet record. Teams should establish who investigates the discrepancy and what information customer support can retrieve. This analysis is particularly relevant when a familiar card interface conceals several independently operated components.
Marqeta’s release does not provide a complete customer eligibility list, consumer fee schedule or independently measured service results. Its claims about speed and cost remain company claims; BijliCoin has not tested the integration. A business should obtain its own contractual and operational answers before treating the announcement as a production specification.
The development is therefore worth following as a change in how card infrastructure may connect to stablecoin infrastructure. The next meaningful evidence will be specific programme availability, documented responsibilities and workable handling of failed or reversed transactions. Those details will tell readers more than the partnership headline alone.
Editorial note: AI-assisted original BijliCoin research, synthesis and analysis from the linked issuer announcement. Company claims and integration performance have not been independently tested. Operational questions are BijliCoin analysis, not confirmed product specifications. The cover is an AI-generated conceptual editorial illustration. No financial or product recommendation is implied.
Sources & context
See our editorial policy or report a correction.